Why laboratory property insurance changes when the lab changes
A biotech company can add material property exposure without opening a second facility. A new freezer, sequencing platform, incubator, analytical instrument, clean-room buildout, or collection of specialized consumables can change both the value at risk and the practical consequences of downtime. The property insurance conversation should begin when operations change, not after a renewal form asks for a single total value.
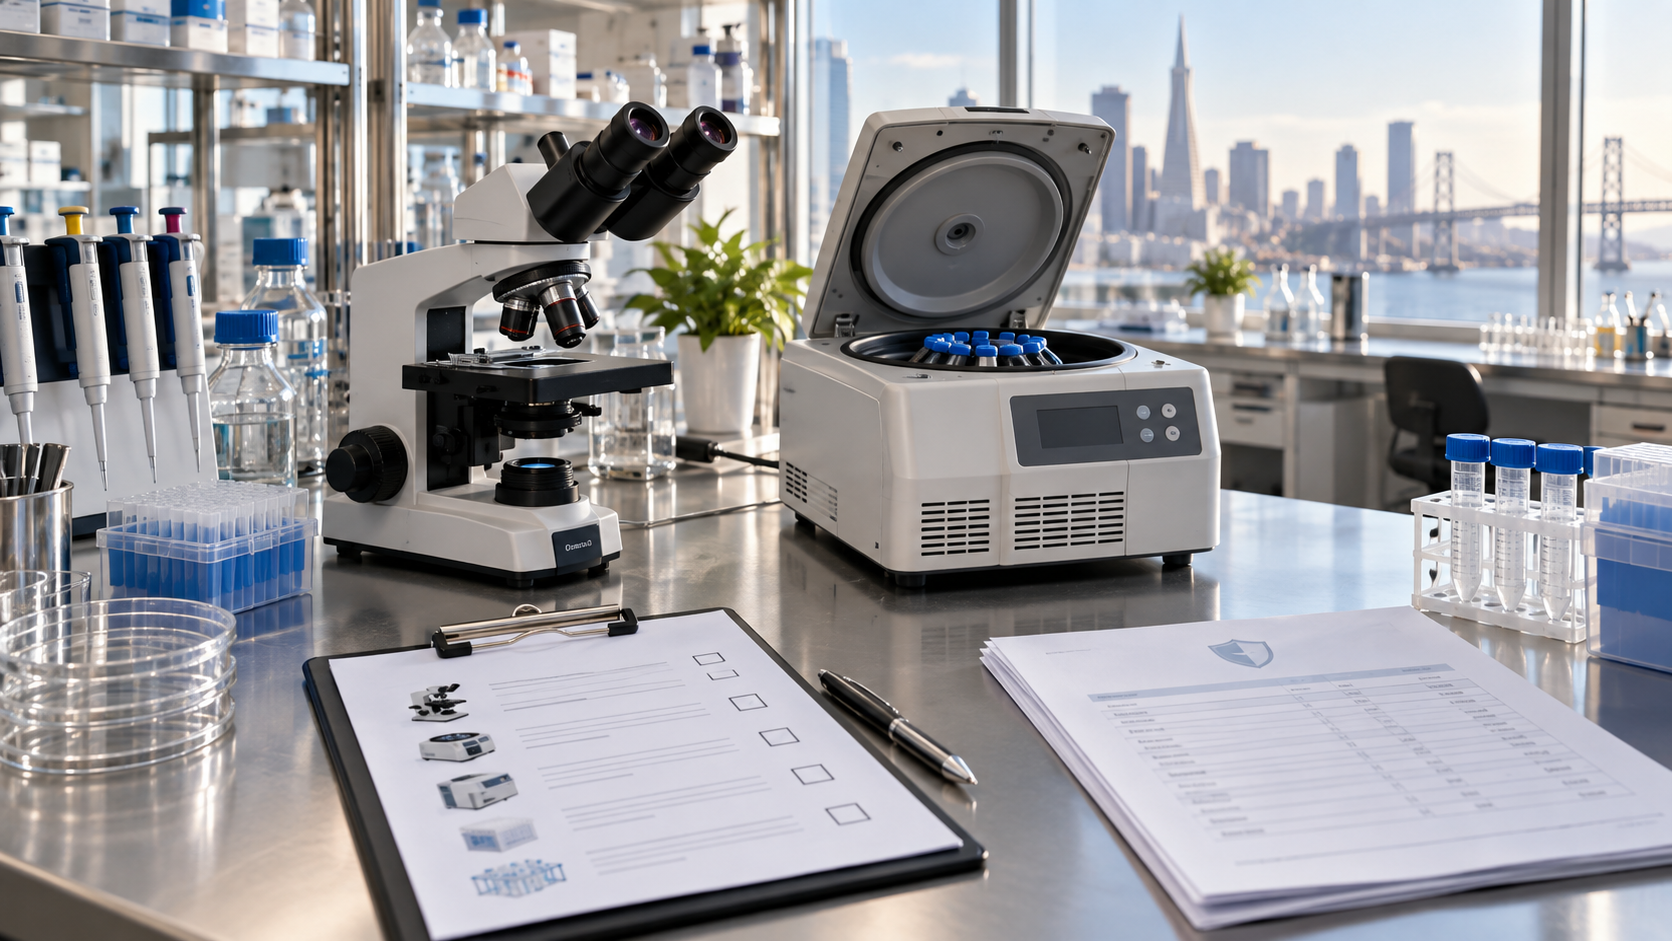
For a Mission Bay laboratory, the useful question is not simply “what did we pay?” It is whether the schedule describes the asset, its location, ownership, replacement path, dependencies, and role in the work. A property policy may use specific definitions, valuation conditions, deductibles, sublimits, and exclusions. The schedule supplies facts for comparing those terms; it is not proof that every listed item will be treated the same way.
- New or upgraded instruments and automated platforms
- Equipment moved into a shared, leased, or third-party facility
- Temperature-sensitive materials and backup-power dependencies
- A critical vendor, utility, or building-system dependency
Build an inventory that is usable beyond the purchasing system
Start with a working register: manufacturer and model, serial number where available, purchase date, original cost, current replacement estimate, owner or lessor, room or facility, and the person who can explain the instrument’s purpose. Add a short note on whether installation, calibration, software, service contracts, or specialized shipping would be required to restore it. This makes the record valuable to finance, operations, and an insurance review.
Separate owned equipment from leased, borrowed, consigned, or customer-owned property. A lease may assign responsibility for loss, require a particular insurance arrangement, or set a valuation basis that does not match the book value in the company ledger. Keep the relevant insurance clause and property schedule with the equipment record so the business can compare contractual responsibility with the terms being considered.
Compare the property-policy mechanics before relying on a total limit
Ask how property is valued: replacement cost, actual cash value, agreed value, or another basis. Then identify deductibles, separate limits, and any conditions that apply to equipment breakdown, electrical disturbance, water damage, off-premises property, or property temporarily in transit. A broad “business personal property” heading may still leave important questions about a specific asset class or loss mechanism.
Business-income and extra-expense provisions deserve their own review. The loss of a laboratory instrument can create costs beyond repair or replacement: temporary capacity, expedited shipping, validation work, rescheduling, and interruption to a research timeline. The issued policy controls which losses are addressed, but gathering the operational timeline now helps reveal whether a proposed waiting period, limit, or definition warrants a question.
Keep the documents that make a later review possible
Maintain invoices, leases, photographs, maintenance records, calibration files, location diagrams, and a quarterly change log. The goal is not to turn the insurance file into a laboratory notebook. It is to preserve the documents that establish what was present, who was responsible, and what it would take to restore the operating capability after a disruption.
Before renewal, ask: Which instrument would stop the business first? Which assets are undervalued because delivery, installation, or validation costs are missing? What does the building lease require? Which materials, utility dependencies, and offsite storage arrangements have changed? Policy wording, declarations, endorsements, and the actual facts control any coverage outcome.
Separate building, business personal property, and property of others
A laboratory business insurance review is clearer when it separates fixtures permanently installed in a suite from movable business personal property and property held for another party. A buildout, a benchtop instrument, a sponsor-owned sample, and a leased analytical platform can have different owners, locations, contracts, and valuation questions. Put each item into the right operational bucket before using a total property number.
For each category, identify whether the company owns, leases, borrows, stores, transports, or has custody of the property. This helps the team read the declarations, schedule, causes-of-loss form, and applicable endorsements with a concrete fact pattern in mind. It does not turn a category label into a conclusion about a loss.
Use a business impact worksheet alongside the equipment schedule
For every critical asset, record the first day of impact, the alternate process, the person approving a workaround, the outside laboratory or vendor that could help, and the revenue or research milestone affected. A business income or extra-expense review becomes more useful when it describes the period of restoration in operational terms rather than relying on a generic downtime estimate.
Leadership should also identify which costs are fixed, which are avoidable, and which would be incurred to resume operations. This gives finance a disciplined basis for renewal and claim-preparation discussions while leaving the policy’s definitions, waiting periods, limits, and conditions to the document-level review.